
Business Loan Services in Chennai: Eligibility, Documents, Process & Funding Options 2026
Getting the right business loan becomes easier when you understand your funding requirements, eligibility, documentation, and available financing options. Whether you are starting a new business, expanding an existing company, purchasing machinery, or managing working capital, a suitable business loan can help you meet your financial needs and support business growth.
From MSME loans and working capital finance to machinery loans and government-backed funding schemes, businesses can explore different financing options based on their eligibility and repayment capacity.
Aanoor Global helps entrepreneurs, startups, MSMEs, and established businesses with Business Loan Services in Chennai, providing professional assistance with loan eligibility assessment, financial documentation, business project reports, funding option evaluation, and loan application preparation.
500+ businesses assisted | 10+ years of experience | 4.9/5 client rating
Services Covered


Business loans are subject to the eligibility criteria, credit assessment, documentation requirements, interest rates, charges and approval policies of the respective bank or financial institution. Aanoor Global does not guarantee loan approval, a specific interest rate, loan amount or processing time. Loan terms vary by lender and applicant profile. This page is for general informational purposes and does not constitute financial advice.
Overview of Business Loan Assistance in Chennai
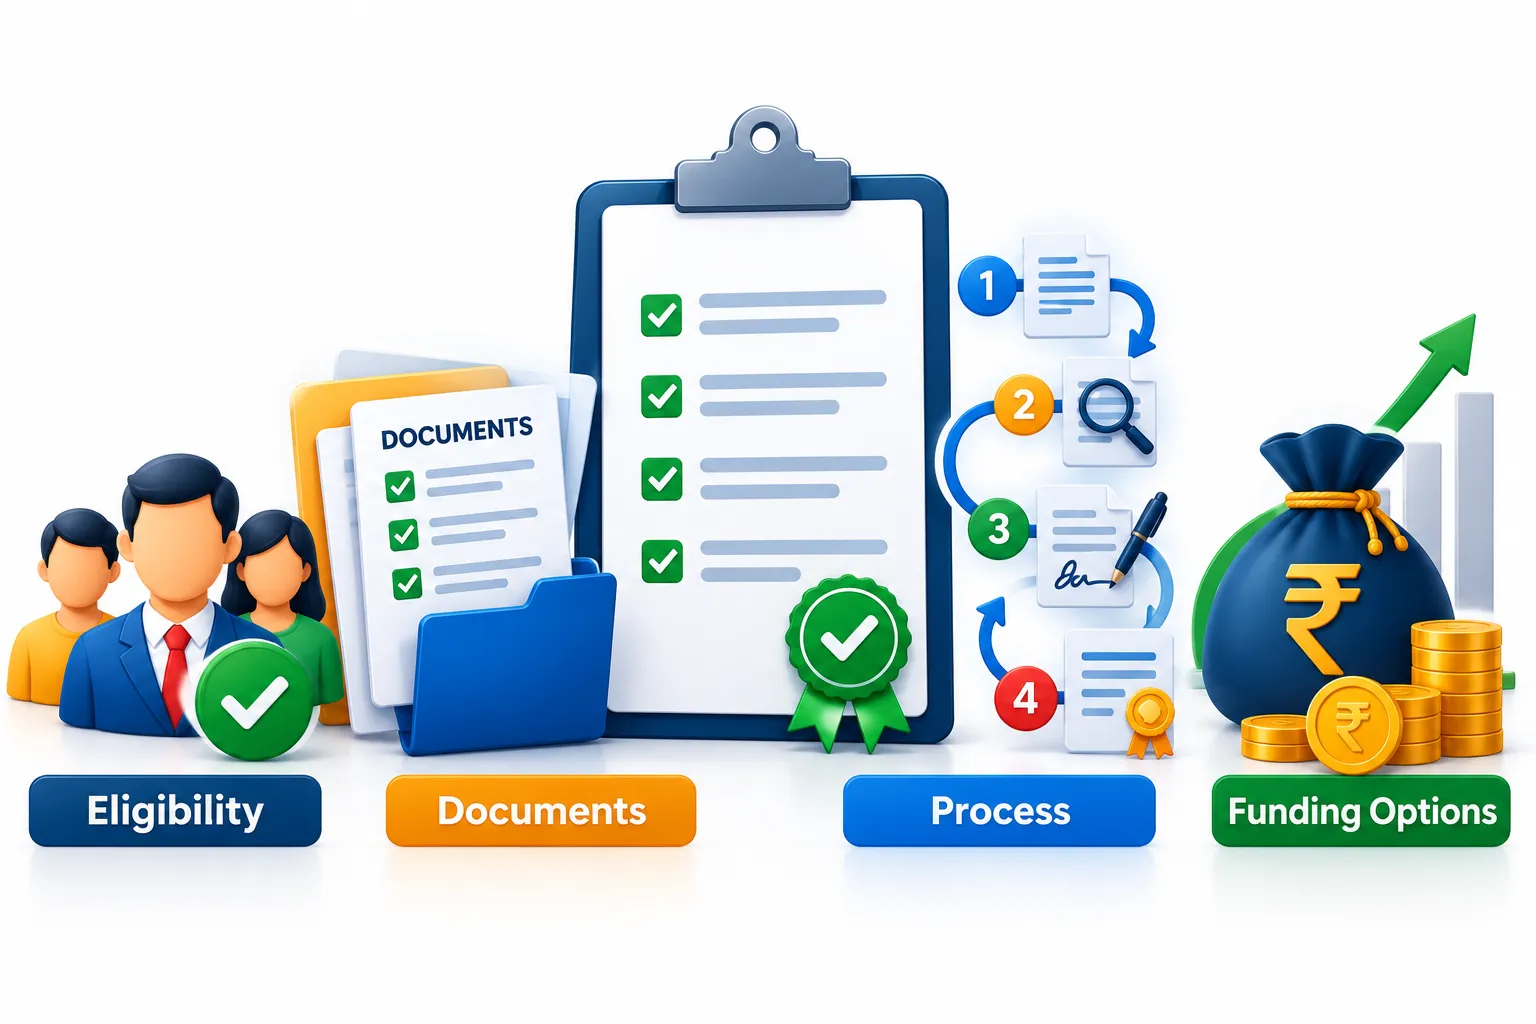
Getting the right business loan becomes easier when you understand your funding requirements, eligibility, documentation, and available financing options. Whether you are starting a new business, expanding an existing company, purchasing machinery, or managing working capital, a suitable business loan can help you meet your financial needs and support business growth. From MSME loans and working capital finance to machinery loans and government-backed funding schemes, businesses can explore different financing options based on their eligibility and repayment capacity.
Aanoor Global helps entrepreneurs, startups, MSMEs, and established businesses with Business Loan Services in Chennai, providing professional assistance with loan eligibility assessment, financial documentation, business project reports, funding option evaluation, and loan application preparation. We also assist with MSME registration, financial statement preparation, business loan documentation, and coordination with banks and financial institutions to help you identify suitable funding opportunities and navigate the loan application process with confidence. Loan approval, interest rates, and disbursement are subject to the lender's eligibility criteria and credit assessment.
Quick Facts
| Detail | Information |
|---|---|
| Service | Business Loan Assistance |
| Location | Chennai, Tamil Nadu |
| Suitable for | Startups, MSMEs, proprietorships, partnerships, LLPs and companies, subject to lender eligibility |
| Common funding needs | Working capital, expansion, machinery, equipment, inventory and other eligible business purposes |
| Common facilities | Term Loan, Working Capital Loan, Cash Credit, Overdraft and Equipment Finance |
| Key assessment factors | Turnover, profitability, cash flow, banking history, credit profile and repayment capacity |
| Common documents | PAN, KYC, business proof, bank statements, financial statements and GST/tax records where applicable |
| MSME documentation | Udyam Registration may support MSME identification and applicable scheme eligibility |
| Approval | Subject to lender assessment |
| Collateral | Depends on lender, facility, borrower profile and applicable security/guarantee arrangements |
| Interest rate | Depends on lender and applicant profile |
| Processing time | Varies by lender, facility and document completeness |
Quick Answer: How to Get a Business Loan in Chennai
A business loan can provide funding for working capital, expansion, machinery, inventory, technology, business setup or other eligible business requirements.
Banks, NBFCs and other authorised lenders may evaluate the business's financial position, banking transactions, repayment capacity, credit history, existing liabilities, business vintage, turnover and supporting documents before making a lending decision.
For eligible MSMEs, Udyam Registration can establish MSME status and may be relevant when assessing applicable schemes and lending opportunities. The official Udyam portal states that registration is free, paperless and based on self-declaration.
Aanoor Global helps businesses prepare for the loan application process by reviewing documentation, organising financial information and assisting with lender application requirements.
Final approval, loan amount, interest rate, collateral requirements and repayment terms are determined by the lender.
What Is a Business Loan?

A business loan is financing obtained by an eligible business from a bank, NBFC or other authorised financial institution for legitimate business-related purposes.
Businesses may use financing for:
The structure of the facility depends on the purpose, amount required, repayment capacity and lender's policies.
Who Can Apply for a Business Loan?

Depending on the lender's eligibility criteria, applicants may include:
A lender may also consider:
Who Should Consider a Business Loan?
A business loan may be considered when there is a clearly identified funding requirement and a realistic repayment plan.
Common requirements include:
Working Capital
Managing inventory, supplier payments, operating expenses and receivables cycles.
Business Expansion
Opening a new branch, increasing production capacity or expanding into a new market.
Machinery and Equipment
Purchasing eligible machinery, equipment or technology.
Inventory Funding
Purchasing stock ahead of seasonal demand or planned growth.
Business Infrastructure
Funding eligible business-related infrastructure and setup requirements.
When Should You Avoid Taking a Business Loan?
Borrowing should be based on actual business requirements and repayment capacity.
Consider postponing or reassessing borrowing if:
- ✕ There is no clear purpose for the funds.
- ✕ Existing debt is already difficult to service.
- ✕ Cash flow is highly unstable.
- ✕ The proposed loan is being used only to cover recurring losses.
- ✕ The requested amount is significantly higher than repayment capacity.
- ✕ The business is depending on uncertain future revenue to make repayments.
- ✕ The total cost of borrowing has not been reviewed.
Before Borrowing, Ask:
Types of Business Loans
Business Term Loan
A defined loan amount repaid over an agreed tenure.
Working Capital Loan
Designed to support short-term operating requirements such as:
Cash Credit Facility
A working-capital facility that may allow an eligible business to draw funds up to an approved limit, subject to lender terms and security arrangements.
Overdraft Facility
Allows an eligible borrower to access funds up to an approved limit, subject to the facility's conditions.
Machinery and Equipment Finance
Funding for eligible machinery, equipment or technology purchases, particularly relevant to manufacturing, engineering, healthcare, logistics and other asset-intensive businesses.
Business Loan Eligibility
There is no single eligibility formula applicable to every lender.
Business Vintage
Some lenders may require the business to have operated for a specified period.
Turnover
Annual revenue may be reviewed to understand business scale.
Profitability and Cash Flow
Financial performance and cash generation can influence repayment-capacity assessment.
Credit Profile
The credit history of the business and/or promoters may be considered depending on the facility.
Existing Liabilities
Current loans and repayment obligations can affect additional borrowing capacity.
Banking Transactions
Recent bank statements can help the lender assess business receipts, expenses and repayment patterns.
Tax and GST Records
GST returns and income-tax records may be requested where applicable.
How Much Business Loan Can You Get?
There is no universal loan amount available to every business.
A lender may consider:
A business with strong and consistent financial performance may have a different borrowing capacity from a newly established business with limited financial history.
Rather than applying for the maximum possible amount, businesses should calculate the amount actually required and assess whether the expected repayment fits projected cash flow.
The final loan amount is determined by the lender after its credit assessment.
Documents Required for a Business Loan
Exact documentation varies by lender and applicant.
Business and KYC Documents
- ✓ PAN card
- ✓ Aadhaar or other accepted identity proof
- ✓ Address proof
- ✓ Business registration documents
- ✓ Partnership deed, where applicable
- ✓ LLP agreement, where applicable
- ✓ Certificate of Incorporation, where applicable
- ✓ Udyam Registration Certificate, where applicable
- ✓ GST registration certificate, where applicable
Financial Documents
- ✓ Income-tax returns
- ✓ Profit and loss statements
- ✓ Balance sheets
- ✓ Financial statements
- ✓ GST returns
- ✓ Bank statements
- ✓ Existing loan statements, where applicable
Company Documents
Companies and LLPs may additionally be asked for:
- ✓ MOA and AOA
- ✓ LLP Agreement
- ✓ Board resolution
- ✓ Director/partner KYC
- ✓ Shareholding details
- ✓ Authorised signatory documents
Business-Related Documents
Depending on the loan purpose:
- ✓ Business plan
- ✓ Project report
- ✓ Machinery quotation
- ✓ Equipment quotation
- ✓ Purchase orders
- ✓ Supplier quotations
- ✓ Projected financial statements
- ✓ Property documents, where applicable
- ✓ Other lender-specific documents
Business Loan Process in Chennai
Identify the Funding Requirement
Determine:
- How much funding is required?
- Why is the funding required?
- How will it be used?
- What repayment period is realistic?
- What existing liabilities does the business have?
Review Eligibility
Assess:
- Turnover
- Profitability
- Cash flow
- Banking history
- Credit profile
- Existing loans
- GST and tax compliance
- Business vintage
Review MSME/Udyam Status
If the business qualifies as an MSME, check whether Udyam Registration is applicable. The official Udyam portal confirms that MSME registration is free, paperless and based on self-declaration.
Organise Financial Documents
Prepare the required:
- Bank statements
- ITRs
- GST returns
- Financial statements
- Business registration documents
- Existing loan details
- Project reports or quotations, where applicable
Prepare the Application
The application should clearly explain:
- Business activity
- Funding requirement
- Requested amount
- Purpose of funds
- Financial position
- Repayment capacity
- Supporting documents
Submit to the Appropriate Lender
The application may be submitted to a suitable bank, NBFC or other authorised lending institution based on the applicant's requirements and eligibility.
Lender Assessment
The lender may conduct:
- Document verification
- Credit assessment
- Financial analysis
- Banking analysis
- Business verification
- Promoter/director assessment
- Security evaluation, where applicable
Sanction and Documentation
If approved, the sanction terms may specify:
- Loan amount
- Interest rate
- Tenure
- Repayment schedule
- Processing charges
- Security requirements
- Other applicable conditions
Review the sanction terms carefully before accepting them.
Disbursement
After completion of the lender's documentation and applicable conditions, the approved amount is disbursed according to the facility terms.
Business Loan Processing Time
There is no universal processing time for all business loans.
Some straightforward MSME applications may be processed within several working days, while secured or more complex facilities can take longer.
Factors affecting processing time include:
What Affects Business Loan Approval?
Loan approval depends on the lender's overall assessment. Important factors may include:
Credit History
Past repayment behaviour may affect the credit assessment.
Business Cash Flow
Consistent business receipts can help demonstrate repayment capacity.
Financial Performance
Turnover, profitability and financial stability may influence the assessment.
Existing Debt
High existing obligations may affect additional borrowing capacity.
Banking Behaviour
Irregular transactions, cheque returns or overdue payments may lead to additional questions.
Documentation
Incomplete or inconsistent records can delay assessment.
Loan Purpose
A clearly defined funding requirement can make the application easier to assess.
Secured vs Unsecured Business Loans
| Feature | Secured Business Loan | Unsecured Business Loan |
|---|---|---|
| Collateral | May be required | Generally no conventional collateral |
| Assessment | Borrower + security may be assessed | Greater emphasis on borrower/business profile |
| Loan amount | Depends on lender and security | Depends on lender and applicant profile |
| Documentation | May include security documents | Usually fewer security-related documents |
| Interest | Depends on lender and risk profile | Depends on lender and risk profile |
| Approval | Subject to lender assessment | Subject to lender assessment |
Business Loan vs Working Capital Loan
| Feature | Business Term Loan | Working Capital Facility |
|---|---|---|
| Main purpose | Longer-term business requirements | Day-to-day operating cash flow |
| Common use | Expansion, equipment, infrastructure | Inventory, receivables and operating expenses |
| Repayment | Usually structured over a defined tenure | Depends on facility |
| Funding pattern | Defined loan amount | May operate through an approved limit |
| Suitability | Planned capital expenditure | Short-term cash-flow requirements |
The appropriate facility depends on the business's funding requirement, financial position and lender assessment.
MSME Business Loans and Udyam Registration
Eligible MSMEs may explore business-finance products and applicable government-supported lending programmes. Current MSME classification under the Udyam framework is:
| Enterprise | Investment Limit | Turnover Limit |
|---|---|---|
| Micro | Up to ₹2.5 crore | Up to ₹10 crore |
| Small | Up to ₹25 crore | Up to ₹100 crore |
| Medium | Up to ₹125 crore | Up to ₹500 crore |
These thresholds are reflected on the current official Udyam portal. Udyam Registration itself is free and paperless through the official Government of India portal.
Official Udyam portal: udyamregistration.gov.inCGTMSE Guarantee Cover
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) provides guarantee support to eligible lending institutions for eligible credit facilities extended to qualifying Micro and Small Enterprises.
Under the current CGTMSE framework, eligible credit facilities can be covered up to ₹10 crore per eligible borrower, subject to the applicable scheme conditions.
CGTMSE does not directly provide loans. It provides guarantee support to its Member Lending Institutions.
The current CGTMSE information also states that the guarantee ceiling has been increased to ₹10 crore.
Important: CGTMSE coverage does not mean:
- ✕ Automatic loan approval
- ✕ Automatic ₹10 crore funding
- ✕ Guaranteed approval
- ✕ Guaranteed interest rate
- ✕ No credit assessment
The lender still assesses the borrower's eligibility, viability, repayment capacity and other applicable conditions.
Official CGTMSE website: CGTMSEBusiness Loan Interest Rates and Charges
There is no single interest rate applicable to every business loan.
Pricing may depend on:
Before accepting financing, compare the total cost of borrowing, not just the headline interest rate. Review:
For digital lending by regulated entities, RBI guidance requires disclosure of the all-inclusive cost as the Annual Percentage Rate (APR) and inclusion of APR in the Key Fact Statement.
Official RBI website: Reserve Bank of IndiaBusiness Loan EMI Calculator
Before applying for a business loan, use an EMI calculator to estimate the potential monthly repayment based on:
An EMI estimate can help you assess whether the proposed repayment fits within projected business cash flow.
A longer tenure may reduce the monthly EMI but can increase the total interest paid over the repayment period.
Business Loan for Startups
Startups may have limited operating history, making their assessment different from established businesses. Before applying, prepare:
Startups should assess how loan repayments will fit into projected cash flow before taking on debt.
Business Loan for Small Businesses
Small businesses may seek finance for:
Maintaining organised accounting, tax and banking records can help make the lender's assessment more straightforward.
Common Reasons for Business Loan Delays
Incomplete Documents
Missing financial or KYC documents can delay processing.
Information Mismatch
Differences between PAN, GST, bank records and business registration documents can trigger clarification requests.
Unclear Funding Purpose
A vague explanation of the proposed use of funds can make assessment more difficult.
Weak Financial Records
Incomplete financial information can make repayment-capacity assessment harder.
Existing Overdues
Unresolved repayment issues may affect the application.
Incorrect Loan Amount
The requested amount should be aligned with the business's requirement and repayment capacity.
Business Loan Checklist
Before applying:
Illustrative Business Loan Example
A manufacturing business in Ambattur required additional working capital and equipment finance to support planned expansion.
Before approaching a lender, the business reviewed:
The application was then structured around a clearly documented funding requirement rather than simply requesting the maximum possible loan amount. This type of preparation can help organise the lender assessment process.
For publication as a client case study, replace this example with a genuine case and publish only with client permission and verifiable results.
Why Choose Aanoor Global for Business Loan Assistance?
A business-loan application involves more than submitting a form.
The quality and consistency of:
can affect how an application is evaluated.
Our Support Includes
Our Trust Signals
Chennai Business Loan Assistance
Aanoor Global supports businesses across Chennai, including:
Whether you operate a trading business, manufacturing unit, professional service, startup or established MSME, we can help organise the loan-application process around your funding requirement.
Frequently Asked Questions
Q
What is a business loan?
↓
A business loan is financing provided by an eligible bank, NBFC or other authorised lender to an eligible business for approved business-related purposes.
Q
Who can apply for a business loan?
↓
Depending on the lender, proprietorships, partnerships, LLPs, companies, MSMEs, startups and other eligible businesses may apply.
Q
Can a startup get a business loan?
↓
A startup may be eligible for certain business-finance products, subject to lender requirements. Business vintage, financial records, promoter profile, cash flow and other factors can affect the assessment.
Q
Is Udyam Registration required for a business loan?
↓
Not every business loan requires Udyam Registration. However, where the business qualifies as an MSME, Udyam Registration can establish MSME status and may be relevant to applicable lending schemes or benefits. The official portal states that Udyam Registration is free and paperless.
Q
Can I get a business loan without collateral?
↓
Some business-loan facilities may be available without conventional collateral, depending on the lender, borrower profile and applicable guarantee arrangements. Approval is not automatic.
Q
What documents are required for a business loan?
↓
Common documents include KYC, PAN, business registration documents, bank statements, income-tax returns, financial statements, GST records and other lender-specific documents.
Q
How much business loan can I get?
↓
There is no universal loan amount. The lender may assess turnover, profitability, cash flow, credit history, existing liabilities, business vintage, security and repayment capacity.
Q
What is the interest rate for a business loan?
↓
The interest rate depends on the lender, loan product, applicant profile, credit assessment, security and other applicable factors.
Q
How long does business loan processing take?
↓
Processing time varies between lenders and applications. Straightforward applications may move faster, while secured or complex facilities can take longer. Document completeness and lender processing time can significantly affect the timeline.
Q
Can I get a business loan for working capital?
↓
Yes. Eligible businesses may use working-capital facilities for approved operational funding requirements, subject to lender terms.
Q
Can I get a business loan for machinery?
↓
Eligible businesses may obtain machinery or equipment finance from lenders offering such facilities, subject to assessment and lender terms.
Q
What is CGTMSE?
↓
CGTMSE is the Credit Guarantee Fund Trust for Micro and Small Enterprises. It provides guarantee support to eligible lending institutions for eligible credit facilities extended to qualifying MSEs. The current scheme provides coverage for eligible credit facilities up to ₹10 crore per eligible borrower, subject to applicable conditions.
Q
Does CGTMSE directly provide loans?
↓
No. CGTMSE does not directly provide loans or financial assistance. It provides guarantee support through its Member Lending Institutions.
Q
Does CGTMSE guarantee loan approval?
↓
No. CGTMSE coverage does not mean automatic loan approval. The lender independently evaluates the borrower and facility.
Q
Does Aanoor Global provide the loan directly?
↓
Aanoor Global provides business-loan assistance and application support. The actual loan is sanctioned and disbursed by the relevant lender, subject to its eligibility and credit assessment.
Q
Does Aanoor Global guarantee loan approval?
↓
No. Loan approval, interest rate, sanctioned amount, collateral and other terms are determined by the lender.
Start Your Business Loan Application in Chennai
Need funding for working capital, business expansion, machinery, inventory or another business requirement?
Before applying, understand your funding requirement, repayment capacity and documentation.
Aanoor Global can help you prepare a structured business-loan application and organise the supporting documents required by the lender.
Book a Free Business Loan Consultation
Discuss your:
Loan approval, amount, interest rate and final terms remain subject to the respective lender's assessment.
Official Resources
Important Disclaimer
Business-loan eligibility, interest rates, processing charges, security requirements, repayment terms and approval decisions are determined by the respective lender.
Aanoor Global does not guarantee loan approval, a particular interest rate, a specific loan amount or approval within a fixed period.
Businesses should review the lender's sanction letter, Key Fact Statement where applicable, loan agreement, applicable charges and repayment obligations before accepting financing.
Government schemes and MSME lending programmes may have separate eligibility criteria and can change over time. Verify current terms with the relevant government authority or lending institution.
Questions on Business Loan?
Get a free phone consultation with our financial specialists to assess your borrowing capacity, documents, and suitable lending facilities.
Aanoor Global helps entrepreneurs and MSMEs with Business Loan Services in Chennai, providing structured assistance with loan readiness, documentation, project reports, and lender application preparation.
Book Free Consultation